- 30 Oct 2026
- Company Research
- VHM reported Q3 2026 NPAT-MI of VND23.1tn (USD890mn; +2% QoQ and 5.5x YoY), mainly supported by bulk sales recognition at Global Gate Ha Long and Saigon Park, as well as continued retail handovers. The underlying property revenue in Q3 2026 (including business cooperation contracts (BCC) and bulk sale transactions recognized as financial income) was VND88.1tn (USD3.4bn; +74% QoQ, 7x YoY), in which bulk sales accounted for ~81% (based on our estimate from VHM’s earnings presentation).
- For 9M 2026, NPAT-MI and underlying property revenue both rose 5x YoY to VND71.4tn (USD2.7bn) and VND200.1tn (USD7.7bn), respectively. Per our estimate, bulk sales recognition contributed ~79% of the 9M 2026 underlying property revenue. As 9M 2026 NPAT-MI exceeded our full-year 2026F forecast by 19%, we see potential upside to our earnings forecast, pending a fuller review.
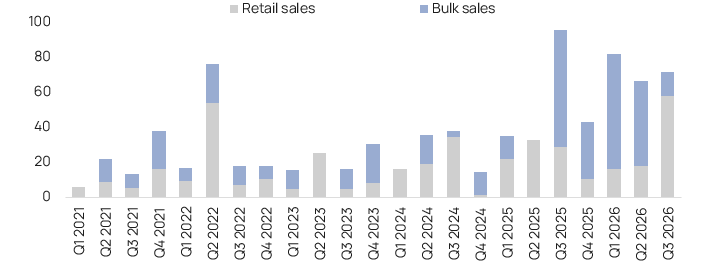
- Q3 2026 presales were VND71.5tn (USD2.8bn; +8% QoQ but -25% YoY; with retail sales contributing ~81%), mainly from Saigon Park, Global Gate Ha Long, Green City, and Green Paradise. Per VHM, the strong QoQ improvement in retail presales was supported by enhanced sales incentives, including loyalty programs, vouchers, and five-year fixed-rate mortgage packages, as well as the launch of more mid-priced products.
- 9M 2026 presales increased 35% YoY to VND219tn (USD8.4bn), with retail sales contributing ~39% of the total. By project, Green Paradise accounted for ~28%, Saigon Park ~27%, and Global Gate Ha Long ~25%.
- As the 9M 2026 presales complete 75% of our 2026F forecast, we foresee insignificant changes to our full-year projection, pending a fuller review.
- End-Q3 2026 unbilled bookings stood at VND185.6tn (USD7.1bn; -6% QoQ, -17% YoY).
- Q4 2026G presales plan: Management expects presales to be driven by subsequent-phase launches at Green Paradise, Global Gate Ha Long, Saigon Park, and Hai Van Bay, with a potential contribution from Global Sportia toward end-2026G.
- The net debt-to-equity ratio (calculated as gross debt less cash and short-term deposits, divided by total equity) increased to 64.5% at end-Q3 2026, vs 56.1% at end-Q2 2026, and vs 38.1% at end-2025.
Figure 1: VHM’s 9M 2026 results
VND bn | 9M 2025 | 9M | YoY | 2026F | 9M 2026 as | Vietcap’s comments on 9M 2026 results |
Net revenue | 50,413 | 202,586 | 302% | 199,594 | 101% |
|
| 20,808 | 170,070 | 717% | 152,679 | 111% | * VHM’s 9M 2026 underlying property revenue increased 5.0x YoY to VND200.1tn (USD7.7bn), with key contributors: Green Paradise (23%), Global Gate Ha Long (22%), Ocean Park 2&3 (20%), and Saigon Park (13%). |
| 29,605 | 32,516 | 10% | 46,916 | 69% | * Mainly construction services. |
|
|
|
|
|
|
|
Gross profit | 17,618 | 118,625 | 573% | 88,824 | 134% |
|
| 6,120 | 113,987 | 1763% | 80,564 | 141% | |
| 11,498 | 4,639 | -60% | 8,260 | 56% |
|
|
|
|
|
|
|
|
SG&A expenses | -4,639 | -6,238 | 34% | -15,855 | 39% |
|
EBIT | 12,979 | 112,387 | 766% | 72,969 | 154% | |
Financial income | 21,831 | 14,321 | -34% | 30,862 | 46% |
|
| 6,034 | 6,426 | 6% | 17,923 | 36% | * Includes retail handovers at the Royal Island and Wonder City projects. |
| 15,797 | 7,895 | -50% | 12,939 | 61% | |
Financial expenses | -16,828 | -33,433 | 99% | -24,767 | 135% | |
Other gain/loss | 311 | -465 | N.M. | 0 | N.M. |
|
PBT | 18,293 | 92,811 | 407% | 79,065 | 117% |
|
PAT | 15,313 | 75,059 | 390% | 63,252 | 119% |
|
NPAT-MI | 14,381 | 71,381 | 396% | 59,928 | 119% | * 9M 2026 NPAT-MI surged 5x YoY, mainly driven by strong bulk sales recognition, offsetting higher YoY financial expenses. * As the 9M 2026 NPAT-MI exceeds our full-year forecast, we foresee upside potential to our 2026F earnings forecast, pending a fuller review. |
|
|
|
|
|
| |
Gross margin % | 34.9% | 58.6% |
| 44.5% |
|
|
| 29.4% | 67.0% |
| 52.8% |
|
|
| 38.8% | 14.3% |
| 17.6% |
|
|
SG&A as % sales | 9.2% | 3.1% |
| 7.9% |
|
|
EBIT margin % | 25.7% | 55.5% |
| 36.6% |
|
|
Effective tax rate % | 16.3% | 19.1% |
| 20.0% |
|
|
NPAT-MI margin % | 28.5% | 35.2% |
| 30.0% |
|
|
Source: VHM, Vietcap forecasts (last updated on August 28, 2026). Note: (*) Vingroup signed a business cooperation contract (BCC) with VHM to transfer the economic interest of real estate developments that are not injected into VHM due to the complexity of paperwork. Thus, VHM records all gains via financial income.
Figure 2: VHM’s quarterly presales results (VND tn)
Source: VHM, Vietcap compilation
Powered by Froala Editor